Crypto Invoicing for Accountants: Reconciliation, Exports, and Client Onboarding
Guide for accountants serving crypto-invoicing clients — reconciliation workflows, CSV exports, tx hash audit trails, FMV recording, and onboarding checklist for USDC invoice businesses.
Do this next
Create a crypto invoice
- Quote the invoice in fiat.
- Client pays USDC, USDT, or EURC.
- Funds settle to a wallet you already control.
TL;DR
Accountants reconcile crypto invoices by matching invoice numbers to on-chain transaction hashes, recording fair market value at receipt in functional currency, and using platform exports (CSV/JSON) rather than block explorer screenshots. Client onboarding requires settlement wallet documentation, network list, and monthly export cadence. Settlematic Collect exports invoice ID, fiat amount, crypto amount, tx hash, and timestamps — send clients the demo link to preview data fields.
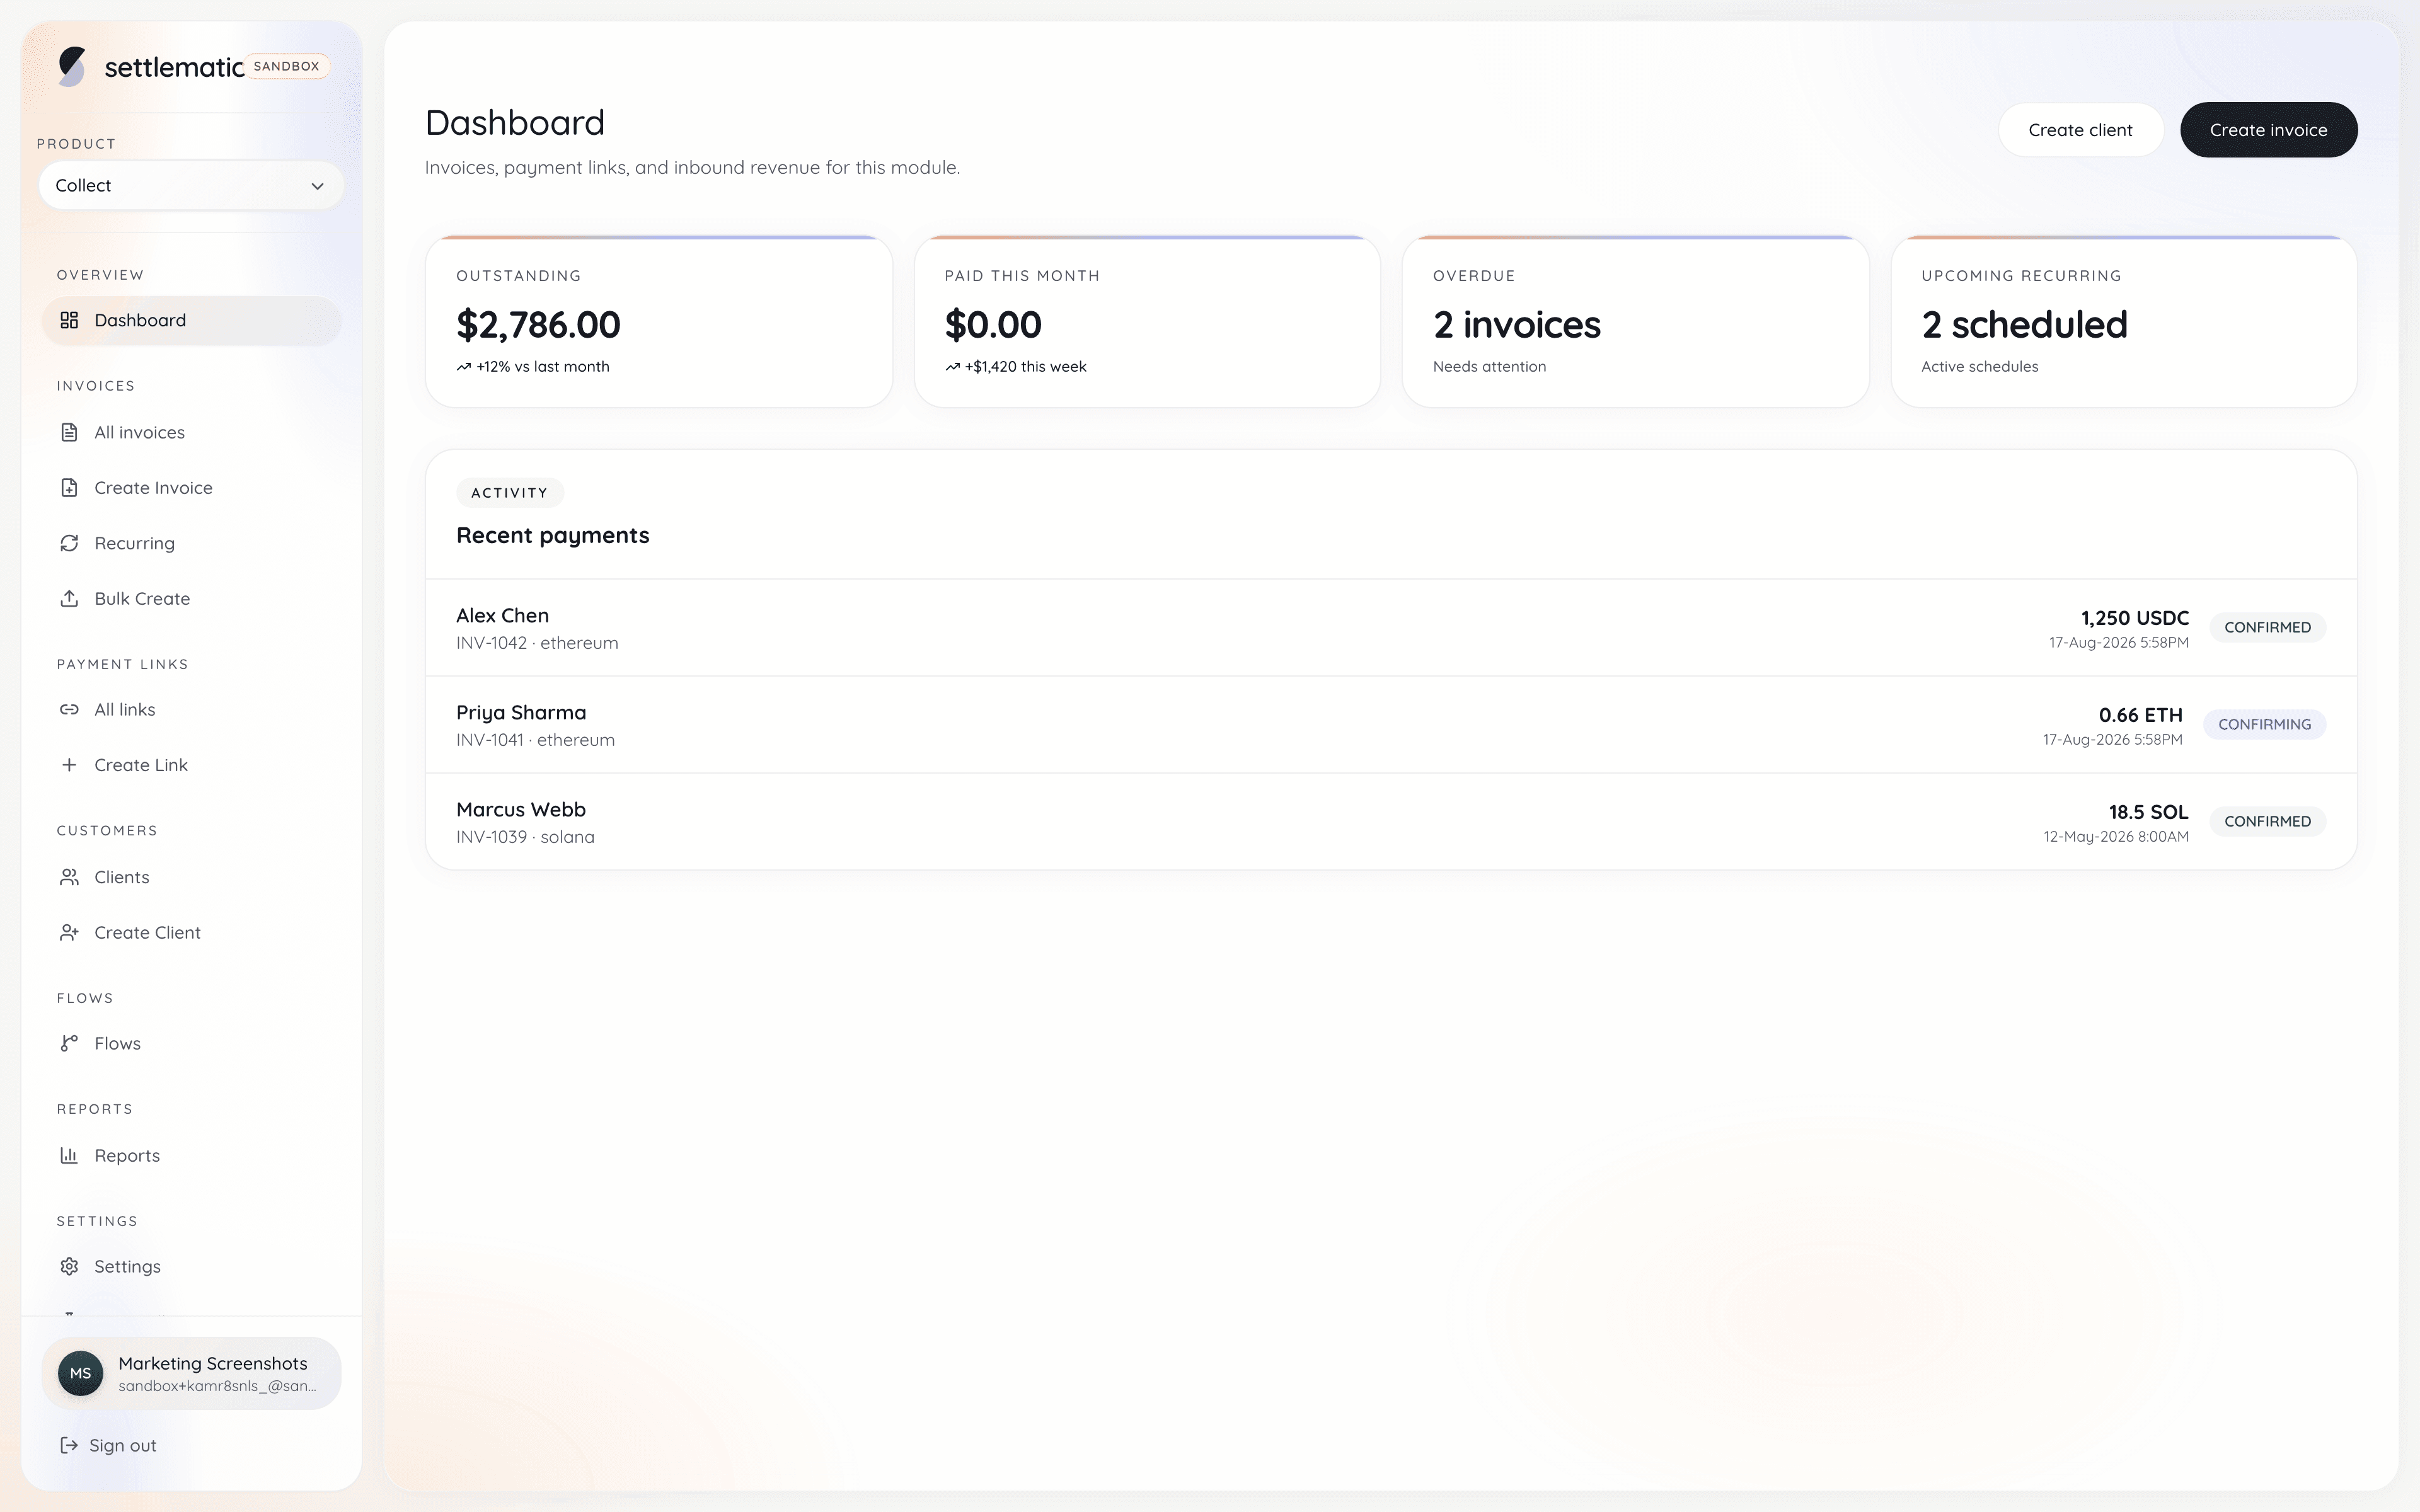
Your client announces they are "switching to USDC invoices" — and suddenly the AP inbox fills with transaction hashes instead of bank references. That is not chaos; it is a different reconciliation grammar. This guide gives accountants and bookkeepers a practical framework for serving merchants who invoice in USD and settle on-chain.
What changes vs traditional invoicing
| Traditional | Crypto invoicing |
|---|---|
| Bank statement line | On-chain tx hash |
| Wire reference memo | Unique deposit address per invoice |
| Settlement delay 2–5 days | Minutes |
| Bank as source of truth | Invoice platform + chain explorer |
| Single currency | Functional currency + USDC asset account |
What does not change: revenue recognition rules, invoice as source document, need for invoice number ↔ payment matching, tax reporting obligations.
Core reconciliation equation
For each paid invoice period:
Break any link — missing hash, wrong amount, wrong invoice number — and month-end stalls.
Professional crypto invoicing platforms export all four legs. Manual wallet merchants send screenshots — unacceptable at scale.
Export fields accountants should require
When onboarding crypto-invoicing clients, require monthly exports containing:
| Field | Purpose |
|---|---|
| Invoice number | Primary match key |
| Issue date / due date | AR aging |
| Customer name | AR subledger |
| Invoice amount (fiat) | Contract obligation |
| Crypto asset | USDC, EURC, etc. |
| Crypto amount received | Settlement verification |
| Network | Explorer selection |
| Transaction hash / signature | Audit trail |
| Payment timestamp (UTC) | FMV date |
| Payment status | open / partial / paid |
| Platform invoice ID | Support tickets |
Settlematic Collect provides these fields in CSV/JSON exports. Verify format before first close — pull sample from demo.
Chart of accounts setup
Typical US client:
| Account | Type | Use |
|---|---|---|
| 1100 USDC Wallet | Asset | On-chain balance |
| 4000 Service Revenue | Income | Invoice recognition |
| 1200 Accounts Receivable | Asset | Open invoices (if accrual) |
EU client with EUR functional currency:
- Invoice may quote USD; record EUR FMV at receipt using ECB or HMRC rate on payment date
- USDC held — mark-to-market if required by accounting framework
Consult framework (GAAP, IFRS, cash vs accrual) — crypto rail does not change framework choice.
Cash vs accrual with crypto invoices
Cash basis: recognize revenue when on-chain payment confirms — matches detection timestamp in export.
Accrual basis: recognize at invoice issue; payment clears AR:
Partial payments split AR reduction. Platform partial status fields matter.
Reconciliation workflow (monthly)
Step 1: Import open invoice report
Beginning of month: list open AR from prior period exports.
Step 2: Import paid invoice export
All invoices marked paid during month with tx hashes.
Step 3: Spot-check on explorer
Sample 10–20% of payments:
- Hash resolves on correct network explorer
- Amount and token match export
- Timestamp within reasonable window of export
Full 100% hash verification optional at low volume; mandatory for high-risk clients.
Step 4: Match exceptions
| Exception | Resolution |
|---|---|
| Paid in export, no hash | Platform support ticket |
| Hash on chain, not in export | Manual payment to old address — client error |
| Amount mismatch | Partial payment or tolerance policy |
| Duplicate hash two invoices | Critical bug — escalate immediately |
Automatic detection should prevent duplicate hash assignment — if seen, data integrity issue.
Step 5: Wallet balance tie-out
End-of-month USDC on-chain balance (sum of wallets client controls) should reconcile to:
Platform export gives receipt side; client provides outflow records.
Step 6: Post adjusting entries
FX adjustments if functional currency not USD. Fee expenses if client paid gas from business wallet (usually immaterial on Solana/Base).
Client onboarding checklist (send to new crypto invoice clients)
Week 0 — Information gathering
- [ ] Business legal name and tax IDs
- [ ] Accounting method (cash/accrual)
- [ ] Functional currency
- [ ] List of settlement wallet addresses (document pubkey/0x — not seed phrases)
- [ ] Networks used (Solana, Base, Polygon, etc.)
- [ ] Invoicing platform access (read-only if available) or monthly export commitment
- [ ] Sample invoice PDF + payment link format
Week 1 — Process agreement
- [ ] Client exports by 5th business day each month
- [ ] Naming convention for export files (2026-08-settlematic-paid.csv)
- [ ] Single point of contact for "I paid but invoice open" disputes
- [ ] Policy on USDC = USD 1:1 or FMV per transaction
Week 2 — Parallel run
- [ ] Reconcile one month alongside client's prior method
- [ ] Resolve discrepancies before solo reliance
Share what is a crypto invoice if client team needs education.
Onboarding clients who use manual wallet addresses
If client refuses platform (red flag for accountant workload):
- Insist on per-invoice spreadsheet: invoice #, address, expected amount, hash, date
- Charge higher fee — manual explorer reconciliation is labor-intensive
- Recommend Settlematic Collect migration — ROI on subscription vs billable hours usually obvious
Tax reporting coordination
Accountants prepare:
- US: Schedule C / 1120 revenue totals; 1099 issuance to US contractors client paid (if client's vendors — different from client's own income)
- Client's crypto income: totals from paid invoice exports — tax time guide
- VAT: invoice PDFs must show VAT lines if registered — crypto settlement irrelevant to VAT line presentation
Form 8949 / Schedule D only if client disposes of USDC (sells to fiat) — holding USDC after invoice payment may be non-taxable event until disposal (US treatment; jurisdiction-specific).
Multi-entity and agency clients
Agencies using crypto invoicing for client work need clear entity separation:
- Which entity issued invoice
- Which wallet received funds
- Pass-through billing vs agency revenue
Export metadata fields (entity_id, project_code) help — configure in platform or CSV post-processing.
Crypto invoicing for remote dev teams patterns apply to agency contractor benches.
Internal controls accountants should recommend
| Control | Prevents |
|---|---|
| Multisig treasury | Single-person wallet theft |
| 2FA on invoicing dashboard | Fraudulent invoice creation |
| Settlement wallet change alerts | Attacker redirecting future funds |
| Segregation: creator vs admin | Insider changing settlement config |
| Webhook HMAC verification | Fake paid events if integrated |
Security guide for client-facing memo.
Software integration paths
| Tool | Approach |
|---|---|
| QuickBooks Online | CSV import to bank feed analog — USDC account manual |
| Xero | Manual journal or API middleware |
| NetSuite | Webhook → Celigo/Make → journal (API webhooks) |
| Excel | Pivot exports — fine under $2M revenue |
Native crypto modules in QBO/Xero evolve — exports remain universal fallback.
Common client mistakes accountants fix
- Reusing wallet addresses across invoices — breaks matching
- No invoice numbers on PDF — AR nightmare
- Mixing personal and business wallets — pierces entity veil audit risk
- Recognizing revenue at quote date not payment date (cash basis) — premature
- Ignoring partial payments — AR drift
- No export archive — recreating history from explorer painful
Explaining crypto invoicing to skeptical partners
Partners worry about "crypto risk" — reframe:
> Client uses USDC as a wire replacement. Invoice is USD. Payment proof is cryptographically stronger than wire memo. We reconcile exports, not speculation.
Custodial processor float is riskier for client than non-custodial — custodial comparison.
Fee structure for accountants
Price monthly reconciliation for:
- Export import + matching
- Explorer spot checks
- Wallet tie-out
- Tax prep data formatting
- Client support calls on "where is my payment"
Crypto-native clients often pay faster — optimize for flat monthly fee vs hourly if exports clean.
Sample reconciliation worksheet
Accountants can adapt this monthly template:
| Invoice # | Client | Fiat amt | USDC rcvd | Tx hash | Paid date | Matched? |
|---|---|---|---|---|---|---|
| INV-0041 | Acme Corp | $5,000 | 5000 | 0xabc... | 2026-08-03 | Y |
| INV-0042 | Beta LLC | $3,200 | 3200 | sig... | 2026-08-05 | Y |
Sum matched fiat column = gross receipts input for tax prep. Flag unmatched rows before signing financials.
Advisory services opportunity
Accountants fluent in crypto invoice reconciliation command premium advisory fees:
- Initial setup engagement (chart of accounts, export mapping)
- Monthly close add-on ($200–$800/mo depending volume)
- Year-end tax package with hash audit trail
- Client workshop: "How to read your Settlematic export"
Position as specialization — fewer competitors than generic bookkeeping.
Regulatory record retention by jurisdiction
| Jurisdiction | Typical retention |
|---|---|
| US IRS | 7 years |
| UK HMRC | 5–6 years |
| EU | Varies 5–10 years by member state |
| Canada | 6 years |
Store exports immutably (S3 versioning, Google Vault) — tx hashes verify against chain years later if questioned.
First month with a crypto-native client walkthrough
Week 1: Receive sample export from client; verify column mapping. Week 2: Reconcile one paid invoice end-to-end including explorer spot-check. Week 3: Document client's USDC=USD policy in engagement letter. Week 4: Take over monthly close. Bill onboarding separately — crypto invoice clients require more first-month hours than pure fiat clients, then less ongoing than manual wallet reconciliation.
Year-end close procedures for crypto invoice clients
December close for USDC-invoicing merchants differs from pure fiat clients in three ways: (1) on-chain balance tie-out replaces bank statement import as primary asset verification, (2) tx hash audit samples substitute for bank check images, and (3) no December 31 bank cutoff ambiguity — chain timestamps are UTC and precise.
Year-end checklist:
- [ ] Download full-year paid invoice export (Jan 1–Dec 31 UTC)
- [ ] Sum fiat_amount column by quarter for estimated tax payment validation
- [ ] Reconcile Dec 31 wallet USDC balance to GL asset account
- [ ] Flag any open invoices with on-chain payments not detected — support tickets before signing financials
- [ ] Archive export CSV with SHA-256 hash in engagement file
- [ ] Provide client CPA with largest-10-payments schedule including tx hashes
- [ ] Document any wrong-chain suspense accounts still open — bad debt discussion if unrecoverable
Partners signing audit opinions need comfort that crypto revenue is complete. A 20-transaction hash sample verified on public explorers typically satisfies review scope for clients under $5M revenue. Scale sample size with materiality.
Software stack recommendations by client size
| Client profile | Monthly invoice volume | Recommended stack |
|---|---|---|
| Solo freelancer | 1–15 | Settlematic export → Excel pivot → hand to CPA |
| Small agency | 15–75 | CSV → QuickBooks Online import |
| Growth SaaS | 75–300 | Webhook → middleware → QBO API |
| Mid-market | 300+ | Webhook → NetSuite + dedicated crypto sub-ledger |
Do not recommend clients migrate accounting frameworks solely for crypto — export discipline matters more than tool brand. QuickBooks and Xero both work when column mapping is stable month over month.
Training your firm on crypto invoice reconciliation
Accounting firms serving multiple crypto-native clients should internalize a 90-minute training module:
- Concepts — Non-custodial vs custodial, unique address per invoice, stablecoin ≈ USD for US books.
- Hands-on — Reconcile three sandbox invoices from demo using sample CSV.
- Explorer drill — Verify one Solana signature and one EVM tx hash.
- Exception handling — Partial payment, wrong network, duplicate hash.
- Client communication — Template email requesting missing tx hash.
Certified staff handle crypto clients without partner escalation — billable efficiency improves 40%+ versus learning per engagement. Position crypto invoice specialization in firm marketing; competition is thinner than generic bookkeeping.
Engagement letter language for crypto invoice clients
Include explicit clauses:
- Client provides monthly export by agreed date (default: 5th business day).
- Client maintains non-custodial invoicing platform access or delegates export to firm.
- USDC recorded at face value unless depeg exceeds 2% at receipt (then FMV policy applies).
- Firm not responsible for on-chain recovery of wrong-network payments.
- Additional hourly rate for manual explorer reconciliation beyond included scope.
Clear engagement language prevents scope creep when client sends 200 unstructured wallet screenshots instead of CSV export.
Segregation of duties for crypto accounts receivable
Crypto invoice reconciliation inherits the same internal control expectations as traditional AR — segregation of duties prevents one person from creating fraudulent invoices and marking them paid. Recommended role separation: invoice creators cannot modify settlement wallet configuration; reconciliation preparers cannot post adjusting entries without reviewer sign-off; treasury wallet signers should not have sole access to invoicing platform admin. Small firms with three-person teams approximate segregation through partner review of monthly hash samples and dual approval on settlement address changes.
Document control matrix in engagement file: who exports, who imports to QuickBooks, who spot-checks explorers, who signs financials. Auditors reviewing crypto AR controls ask the same questions as fiat AR — completeness, accuracy, authorization — with tx hash substituting for bank confirmation number. When client uses API automation for invoice creation, verify webhook HMAC configuration was not set by the same engineer who deploys fulfillment code without finance review. Crypto speed does not justify skipping approval gates on high-value invoices.
Peer review standards for transaction hash verification
Explorer spot-check sampling should follow documented methodology, not ad hoc clicking during month-end panic. Recommended approach for clients under five million annual revenue: stratified sample of twenty percent of payments, minimum ten transactions, including all payments above materiality threshold and random selection from remainder. Reviewer independently verifies hash resolves, token contract matches USDC on stated network, amount matches export, and timestamp falls within invoice payment window.
Peer review sign-off belongs on reconciliation worksheet: reviewer name, date, sample size, exceptions noted. When exception found — amount mismatch, wrong mint, duplicate hash — expand sample to one hundred percent for that month until root cause resolved. Train junior staff on Solana signature format versus EVM tx hash before assigning verification — confusing the two wastes partner time and erodes client confidence. Quarterly calibration: two reviewers independently verify same five hashes; disagreement triggers methodology review.
Partners signing compilation reports should note crypto AR methodology in engagement letter exhibits — generic "we reviewed bank statements" language does not cover tx hash sampling. Update firm-wide audit program annually as crypto invoice client count grows. Even ten percent crypto AR clients justify firm-wide training refresh — methodology errors in one engagement create malpractice exposure across the practice.
Accountants serve crypto-invoicing clients by treating tx hashes like wire references and exports like bank statements — with stronger audit trails. Standardize export fields, run monthly reconciliation, and onboard clients to Settlematic Collect before manual chaos accumulates. Preview export format in demo; clients compare pricing against your reconciliation billable hours.
Frequently asked questions
- Is USDC always $1 for books?
- US practice: often yes for practical purposes; document policy. Minor depeg adjustments rare for USDC.
- Do we need separate wallet per invoice on books?
- No — on-chain addresses differ per invoice; books aggregate to USDC asset account. Export maps address → invoice.
- Can client grant accountant read-only dashboard access?
- Platform-dependent — export-only often sufficient for confidentiality.
- How to handle client pays wrong network?
- Usually not detected as paid — invoice stays open. Client must recover via exchange support or pay again correctly. Document as unpaid, not revenue.
- Are platform fees COGS or operating expense?
- Operating expense — software subscription (pricing).
- What if client also accepts wires?
- Two rails — same AR process, different bank vs export reconciliation sections.
- How long retain crypto invoice records?
- Match existing document retention — typically 7 years US tax.