How to Get Paid in Crypto from US and EU Clients
Step-by-step guide to invoicing US and EU clients in crypto: tax, VAT, MiCA, client onboarding, stablecoins, and non-custodial billing with Settlematic.
Do this next
Create a crypto invoice
- Quote the invoice in fiat.
- Client pays USDC, USDT, or EURC.
- Funds settle to a wallet you already control.
TL;DR
Invoice in fiat, accept USDC, record the fiat-equivalent value and transaction hash for every payment, and export clean records for your accountant. CARF reporting from 2026 means platforms share data with tax authorities - good records are the whole game.
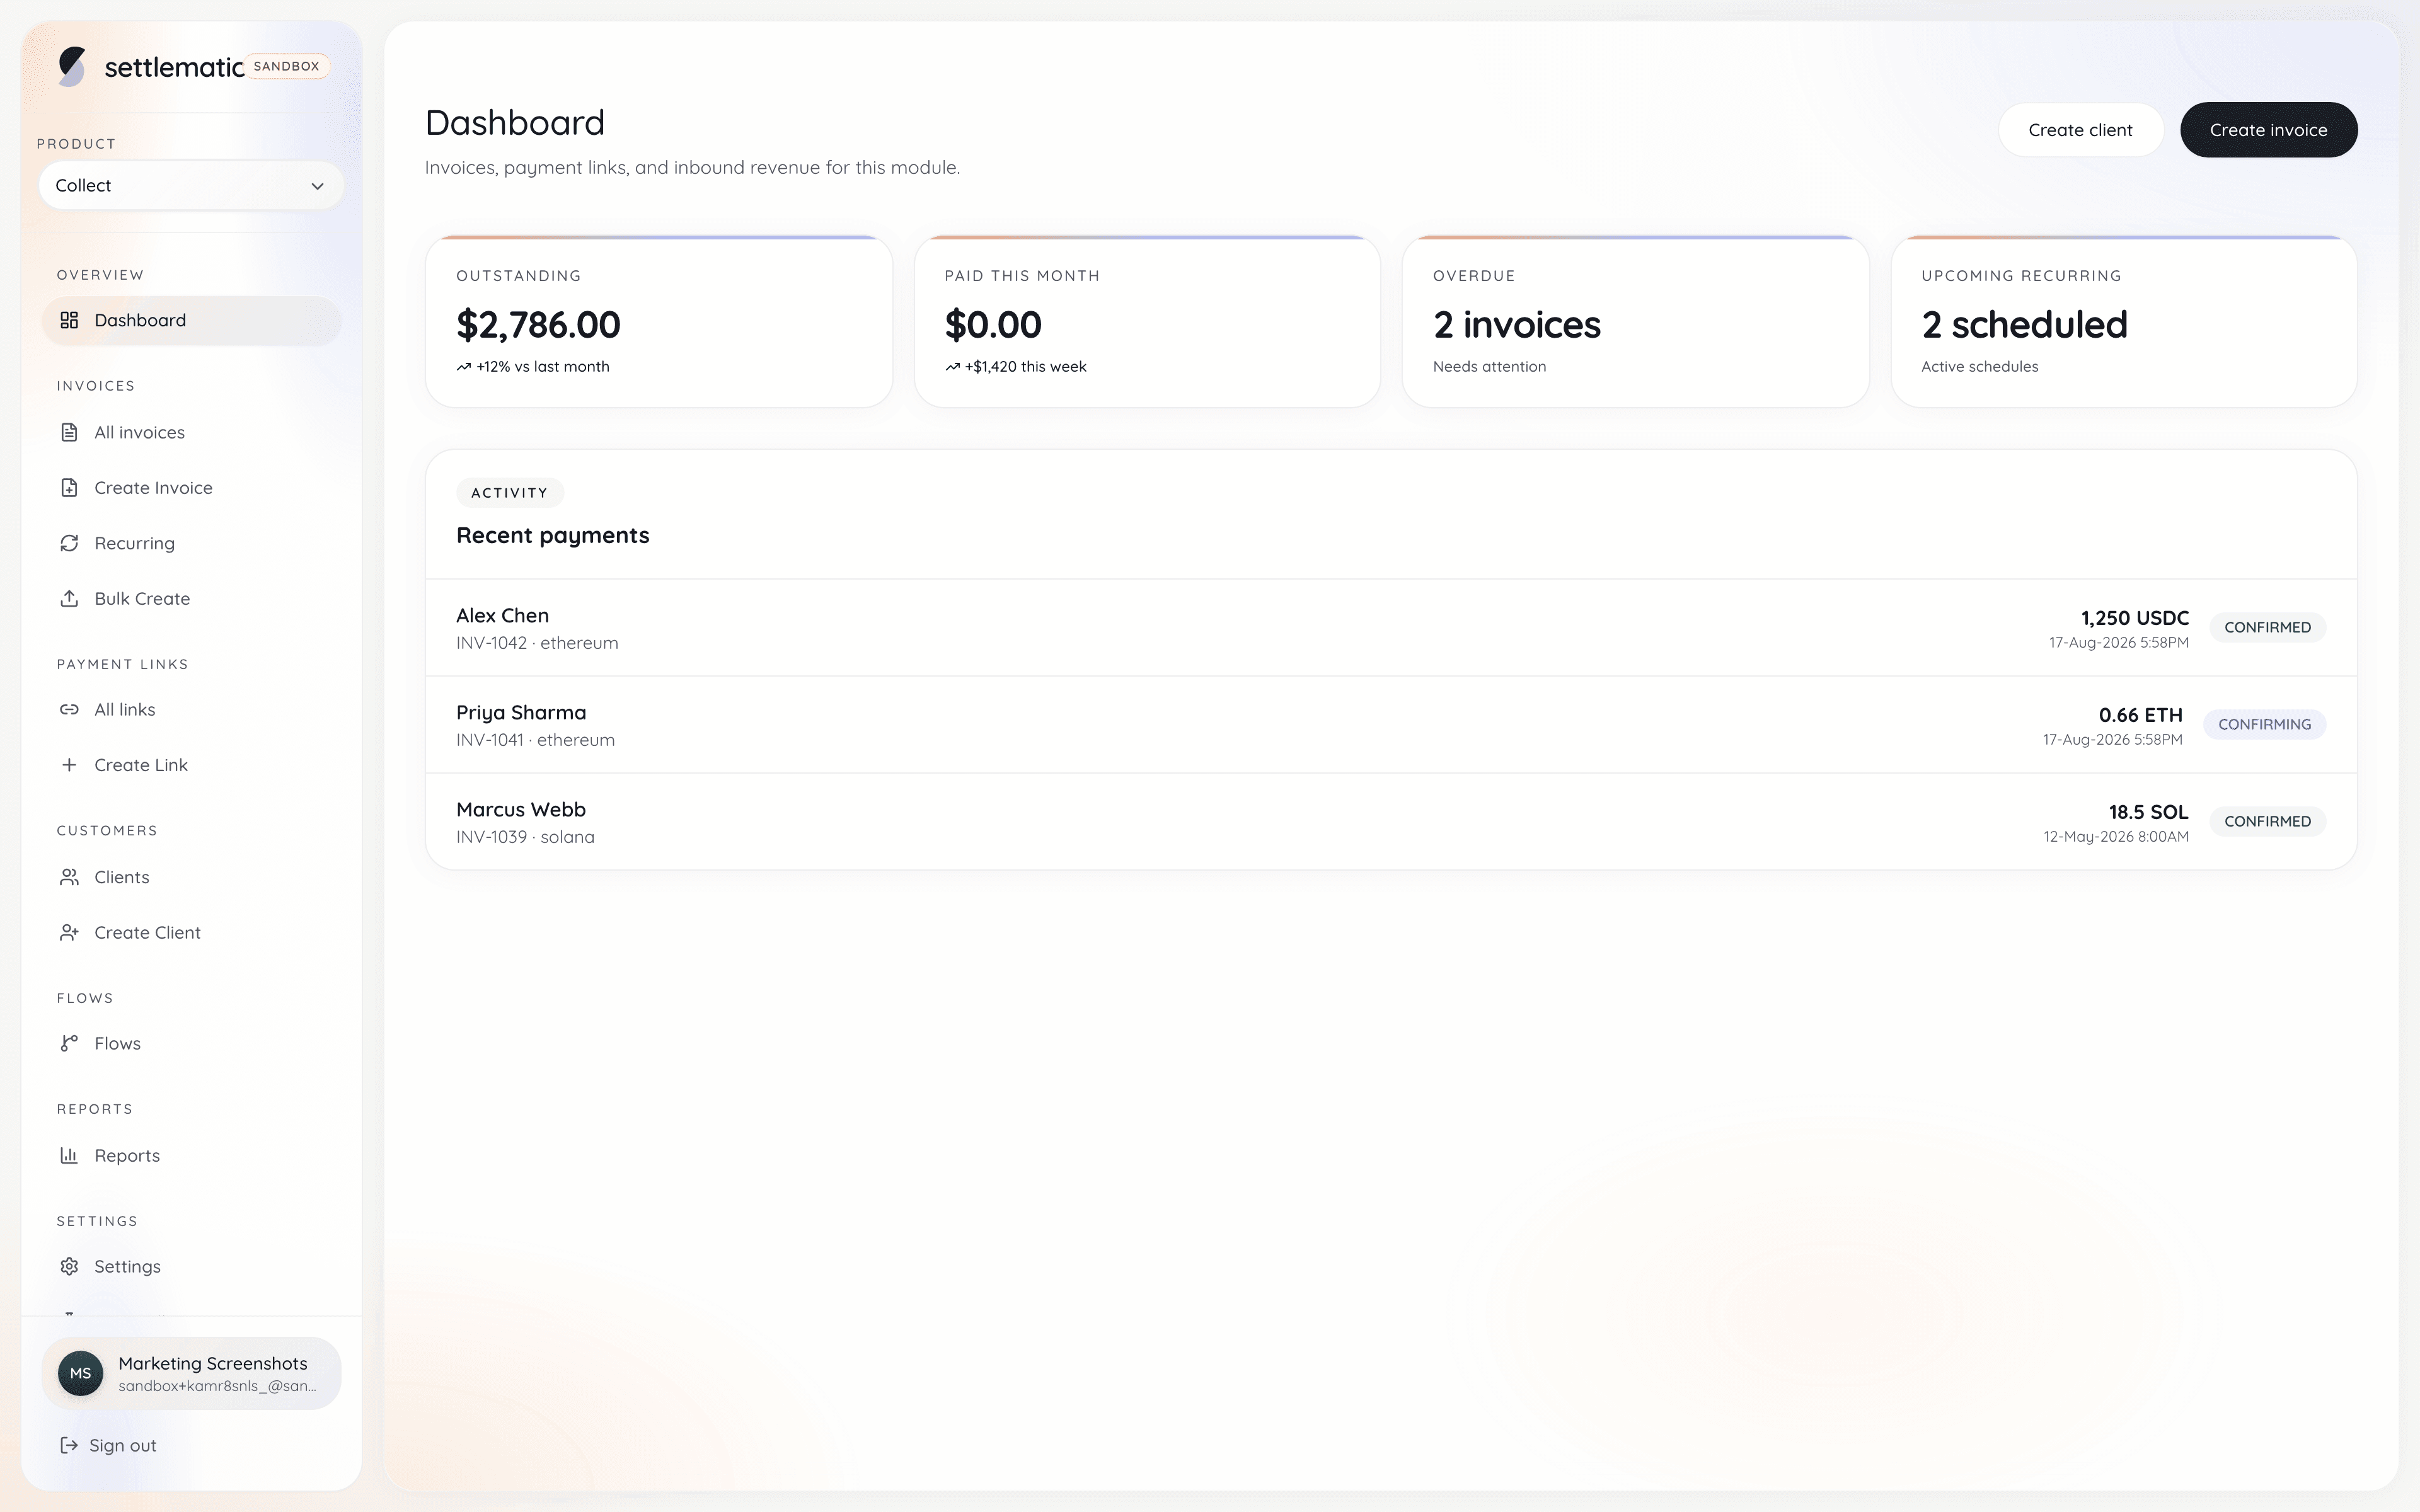
Getting paid in crypto from US and EU clients requires combining compliant invoicing practices, clear client communication about networks and tokens, and tooling that reconciles on-chain payments without custodial intermediaries. Whether you are a US freelancer billing a German GmbH or a EU agency invoicing a Delaware C-corp, the workflow shares a core pattern: quote in fiat for familiarity, settle in stablecoins for speed, document everything for tax authorities, and use branded invoices that finance teams can process like any other vendor bill.
Why US and EU Clients Pay in Crypto in 2026
Cross-border B2B payments traditionally incur wire fees ($25-50 per transfer), SWIFT delays (2-5 business days), and FX spreads. Crypto stablecoin transfers on Solana or Ethereum L2s settle in seconds to minutes for cents in fees.
Client motivations:
- Treasury diversification — holding USDC as operational float
- Speed — same-day settlement for time-sensitive projects
- Reduced FX friction — USDC maps cleanly to USD accounting for US entities
- Vendor preference — you request crypto; client accommodates to win the contract
Your motivations:
- Faster cash flow vs international wire
- Lower receiving fees (no intermediary bank cuts)
- Direct wallet settlement without custodial processor risk
Neither the IRS nor EU tax authorities prohibit crypto invoicing—they require proper income reporting and VAT treatment.
US Client Considerations
Tax and reporting
The IRS treats virtual currency as property. When a US client pays you in crypto, you recognize income at fair market value in USD on the date received (Publication 544, general property transaction principles apply). Maintain records: invoice date, crypto amount, USD value at receipt, tx hash.
If you are a US person receiving payments from US clients:
- Income is reportable regardless of payment rail
- Clients may issue Form 1099-NEC if payments exceed $600 in a calendar year (threshold and rules evolve—verify current IRS guidance)
- Self-employment tax applies to net earnings as usual
Client onboarding for US payers
US corporate AP teams need:
- W-9 on file before first payment
- Invoice matching PO number
- Vendor setup in NetSuite, QuickBooks, or SAP
- Clear instruction whether you accept stablecoins only or also BTC/ETH
Provide a one-page "How to Pay This Invoice" PDF with network, token, amount, and hosted payment link. Link to custom-branding-crypto-invoices patterns for professional presentation.
Stablecoin preference
US clients overwhelmingly prefer USDC on Base, Ethereum, or Solana. USDT remains common but some US corporates avoid it due to reserve transparency concerns. Quote invoices in USD; specify USDC amount at invoice creation with a short validity window if you lock the crypto amount.
EU Client Considerations
VAT and MiCA context
EU B2B invoicing must satisfy VAT Directive requirements where applicable: supplier and customer VAT IDs, taxable base, rate, and reverse-charge language for cross-border B2B services.
MiCA (Markets in Crypto-Assets Regulation) regulates crypto-asset service providers in the EU—it does not prohibit your client from paying invoices in crypto. Your invoicing platform's non-custodial status typically avoids CASP custody licensing; see what-is-non-custodial-crypto-invoicing.
Reverse charge scenarios: if you are a non-EU supplier billing an EU business client for B2B services, VAT often shifts to the client. Include required legal text on invoices. Consult a EU tax advisor for your specific supply chain.
EU client payment behavior
EU finance teams may prefer:
- EUR-denominated invoice with USDC settlement at ECB reference rate
- SEPA for fiat fallback option
- E-invoicing formats (Peppol, Factur-X) for enterprise—crypto platforms may supplement, not replace, for largest accounts
Solana and Ethereum L2 USDC transfers are increasingly familiar to EU crypto-native treasuries, especially in fintech and Web3 sectors.
Choosing Tokens and Networks
| Token | Peg | Common networks | Best for |
|---|---|---|---|
| USDC | USD | Solana, Base, Ethereum | US and global B2B |
| USDT | USD | Ethereum, Tron | Clients with existing USDT treasury |
| EURC | EUR | Ethereum | EU clients wanting euro stablecoin |
| ETH | Variable | Ethereum L2s | Crypto-native clients only |
Default recommendation for cross-border US/EU B2B: USDC on Solana for speed and low fees, or USDC on Base if client's treasury is EVM-centric.
Always specify one network per invoice. Multi-network choice increases wrong-chain payments—see crypto-invoice-paid-wrong-chain.
Step-by-Step: Your First US/EU Crypto Invoice
- Agree terms in contract — Payment in USDC, network, due date, who bears gas fees (usually payer)
- Create invoice in Settlematic — Amount, client details, network, branded template
- Send PDF + payment link — Email AP contact with PO reference
- Client pays from exchange or wallet — Coinbase, Kraken, MetaMask, corporate Fireblocks
- Confirm on-chain — Webhook fires payment_confirmed; see webhook-patterns-crypto-billing
- Export to accounting — QuickBooks/Xero per export-crypto-invoice-data-quickbooks-xero
- Month-end reconcile — how-to-reconcile-crypto-payments-month-end
Client Communication Templates
Email subject
Invoice #1042 — $8,500 USD (USDC on Solana) — [Your Company]
Body essentials
- Invoice attached as PDF
- Payment link: [hosted page]
- Network: Solana Mainnet
- Token: USDC (SPL)
- Amount: 8,500 USDC
- Due date
- Support contact
FAQ for client's AP team
- "Is this legitimate?" — Point to contract, PO, branded invoice
- "Can we pay from Coinbase?" — Yes, withdraw USDC to invoice address on Solana
- "What if we send wrong network?" — Contact immediately; recovery may be possible per recover-wrong-chain-crypto-invoice-payment
Legal and Contract Clauses
Include in master service agreement or invoice terms:
- Accepted tokens and networks (list explicitly)
- Payment finality upon on-chain confirmation (define confirmation count)
- FX/crypto amount locked at invoice issue or due date
- Client responsibility for wrong-chain or wrong-token sends
- Refund policy for overpayment (credit note vs on-chain return)
Non-Custodial Settlement: Why It Matters for International Billing
Custodial processors holding funds during cross-border settlement introduce:
- Licensing uncertainty (EU CASP, US MSB)
- Counterparty risk if processor fails
- Delayed access to funds during sweep windows
Settlematic's non-custodial model routes US and EU client payments directly to your wallet. You control custody; the platform verifies and reconciles. Review pricing and book a demo for high-volume international billing.
Handling Exchange Withdrawal Fees
Clients paying from centralized exchanges pay withdrawal fees that may cause underpayment. Mitigations:
- Round invoice crypto amount slightly below nominal to absorb small fees (document on invoice)
- Allow small tolerance in payment detection (e.g., 0.1% underpayment flagged as partial)
- Instruct clients to cover full invoice amount including withdrawal fee
Sanctions and Compliance Screening
US OFAC and EU sanctions regimes apply regardless of payment rail. Do not accept payment from sanctioned addresses or entities. Some platforms integrate screening; merchants remain responsible for compliance.
Document KYC on large clients where your risk policy requires it. Crypto payment does not eliminate AML obligations for regulated businesses.
Accounting for Multi-Currency Reality
Even with USDC, your functional currency may be EUR or USD. Record:
- Invoice amount in functional currency
- Crypto received and tx hash
- Exchange rate source if converting stablecoin to fiat for reporting
- Gain/loss only if token is non-stable (BTC, ETH) between invoice and receipt dates
QuickBooks Online crypto integrations are evolving; CSV export from Settlematic remains reliable for 2026 workflows.
Scaling to Recurring US/EU Clients
For retainer clients:
- Recurring invoice schedules with same client, new address per invoice (non-custodial reconciliation)
- Saved client profiles with preferred network
- Automated reminders before due date
- Annual 1099 or EU annual summary support via export
Enterprise Procurement and Vendor Onboarding
Large US corporations and EU multinationals require vendor onboarding before first payment—crypto does not bypass procurement. Expect requests for W-9 (US), W-8BEN-E (non-US entities billing US clients), proof of business registration, insurance certificates, and SOC 2 or ISO 27001 from your invoicing vendor if enterprise security reviews extend to subprocessors. Settlematic's non-custodial posture simplifies security questionnaires: no customer funds held, no hot wallet attack surface on merchant payments. Provide a one-page vendor security summary linking to what-is-non-custodial-crypto-invoicing for AP teams unfamiliar with blockchain terminology. Vendor ID assignment in client ERP (SAP vendor number, NetSuite vendor record) must precede crypto payment—invoice PDF should reference that ID in a prominent field.
Treasury Policy Alignment
Corporate treasuries adopting crypto payments publish internal policies: approved tokens (usually USDC only), approved networks (often allowlist of Base, Solana, Ethereum), maximum per-transaction limits, and dual-approval thresholds above $50,000. Align your invoice networks with client allowlists before sending—discovering mismatch after invoice issuance forces void-and-reissue cycles. Offer to join client's vendor webinar explaining payment steps; fifteen minutes of live Q&A prevents weeks of wrong-chain support per crypto-invoice-paid-wrong-chain. Document which team member on client side owns treasury approvals—CFO, AP manager, or dedicated digital assets lead.
Competitive Positioning as Crypto-Friendly Vendor
Accepting crypto can win deals against competitors insisting on wire only—especially for Web3 clients, international startups, and remote-first agencies. Mention crypto acceptance in proposals without making it the headline; position as flexibility alongside wire and ACH. Clients choosing you for crypto capability often expand contract scope once first payment succeeds smoothly. Case studies (anonymized) citing same-day settlement vs five-day SWIFT strengthen sales narratives. Ensure custom branding on first crypto invoice matches proposal professionalism—sloppy first invoice undermines competitive advantage.
Dispute Resolution and Payment Finality
Crypto payments are irreversible once confirmed—unlike card chargebacks. Contracts should define payment finality at N confirmations, dispute windows for service quality (separate from payment reversal), and refund procedures via new on-chain transfer. US clients cannot "charge back" USDC; negotiate credit notes for legitimate service disputes. EU consumer protection rules differ for B2B vs B2C—most agency and consulting invoices are B2B where crypto finality is standard contract term. Keep off-chain communication trails linking payment tx hash to delivered work product for dispute evidence.
Long-Term Client Relationship Management
After successful first crypto payment, save client preferences in Settlematic: preferred network, AP contact email, PO format, typical payment lag from invoice date. Recurring clients appreciate consistent invoice numbering and predictable payment links. Annual summary of total paid via crypto helps clients with their own tax and audit documentation. Cross-sell related capabilities—webhook automation for their fulfillment systems, QuickBooks export for their finance integration—when relationship matures.
Industry-Specific Guidance
Software development agencies billing US startups: USDC on Base aligns with client treasury on Coinbase Base withdrawals; include GitHub repo or sprint ID in invoice line items for client capitalization policies. Design studios billing EU fashion brands: EUR invoice display with USDC settlement at ECB daily rate; include VAT reverse-charge block. Consultants billing Delaware holding companies: holding company AP may be outsourced to Philippines BPO—provide extra-plain-language payment guide with screenshots; wrong-chain rate highest in this segment. Web3 protocols billing other protocols: often mutual USDC on Solana; fastest segment to onboard; still use formal invoices for grant accounting and foundation audits.
Regulatory landscape snapshot (2026)
US and EU regulatory frameworks continue evolving — merchants should monitor but not paralyze:
| Jurisdiction | Relevant framework | Impact on B2B invoicing |
|---|---|---|
| US federal | IRS property treatment | Income at FMV on receipt |
| US state | MTL varies by state | Non-custodial invoicing typically exempt |
| EU | MiCA (CASP licensing) | Non-custodial platforms avoid custody license |
| EU | VAT Directive | Invoice format requirements unchanged |
| UK | FCA crypto promotions | B2B invoicing less affected than retail marketing |
Consult counsel for your entity structure — US LLC billing EU GmbH differs from Estonian OÜ billing Delaware C-corp. Crypto payment method does not eliminate transfer pricing documentation for related-party transactions.
Building a repeatable US/EU client onboarding playbook
Standardize first-client crypto onboarding into a 5-touch sequence:
- Contract signature — Payment terms specify token, network, confirmation count.
- Vendor setup — Client adds you to ERP; you provide W-9/W-8BEN-E.
- Payment guide PDF — Branded one-pager with exchange screenshots for their treasury stack.
- Test invoice — Small amount ($100) before first production invoice.
- Retrospective — 15-minute call after first payment; capture lessons in client profile.
| Touch | Owner | Deliverable |
|---|---|---|
| Contract | Sales/legal | Signed MSA with crypto clause |
| Vendor setup | Client AP | Vendor ID in ERP |
| Payment guide | You | PDF + link to custom branding |
| Test invoice | Finance | Paid $100 invoice on record |
| Retrospective | Account lead | Client preferences documented |
Clients completing all five touches show <2% wrong-chain rate on subsequent invoices — invest onboarding time upfront.
Currency hedging and stablecoin depeg considerations
USDC and EURC depegs are historically brief but non-zero. Merchant policy options:
- Face value — Record $1 per USDC; adjust only if depeg exceeds 2% for 24+ hours.
- FMV daily — Mark USDC to market daily while held — complex for high-volume.
- Immediate off-ramp — Convert to fiat within 24 hours of receipt — minimizes depeg exposure.
Document policy in accounting manual before first invoice. EU clients invoiced in EUR with USDC settlement should reference ECB rate on payment date in export memo for transfer pricing consistency.
Comparison: crypto vs traditional cross-border rails
| Factor | USDC (Solana/Base) | SWIFT wire | Wise/PayPal B2B |
|---|---|---|---|
| US→EU settlement | Minutes | 2–5 days | 1–3 days |
| Fee on $10k | <$1 | $30–$60 | $50–$150 |
| FX spread | Minimal (USD stablecoin) | Bank spread | Platform spread |
| Reversibility | None | Difficult | Limited |
| Audit trail | On-chain tx hash | Wire reference | Platform ID |
| Client AP familiarity | Growing | High | High |
Lead with speed and cost for crypto-native clients; offer wire fallback for traditional enterprises. Many US clients try crypto once and standardize after successful first payment.
Frequently asked questions
- Do I have to pay tax on crypto I receive from a client?
- In most jurisdictions, yes. Crypto received for services is income at its fiat-equivalent value on the date you receive it - ordinary/self-employment income in the US and UK, and member-state-defined income in the EU. A later sale or swap of that crypto can also be a capital gains event. This isn't tax advice; confirm with a professional.
- How do I avoid capital gains tax on crypto payments?
- You can't avoid lawful tax, but you can minimize the capital-gains event by getting paid in a stablecoin like USDC. Because its value tracks the dollar, there's little or no gain between receiving it and converting it - so the messy part of crypto taxation largely disappears. The income event still applies.
- What is CARF and does it affect me?
- The Crypto-Asset Reporting Framework is an OECD standard, effective from January 1, 2026, under which crypto-asset service providers report users' personal and transaction data to tax authorities. If you invoice clients in crypto through a platform, your activity is increasingly visible to tax authorities, so accurate declaration is essential.
- Can I legally invoice US and EU clients in crypto?
- Yes, in most cases. There's no general prohibition on being paid in crypto for legitimate services in the US, EU, or UK; you simply have to report the income and keep records. EU stablecoins fall under MiCA, and you should confirm your specific local VAT and income rules.
- What records do I need to keep for crypto invoices?
- For each payment: invoice number, client, asset and chain, amount, the fiat-equivalent value at receipt, date, transaction hash, and any fees. A proper invoicing tool exports all of this automatically, which is the easiest way to stay audit-ready under CARF.