How to Accept Stablecoin Payments: Complete Business Guide
Learn how to accept stablecoin payments for your business in 2026. Discover USDC, USDT, and EURC integration, zero-take-rate non-custodial settlement, and compliance.
Do this next
Create a crypto invoice
- Quote the invoice in fiat.
- Client pays USDC, USDT, or EURC.
- Funds settle to a wallet you already control.
TL;DR
To accept stablecoin payments, businesses issue fiat-denominated invoices or checkout links that generate unique deposit addresses for assets like USDC, USDT, and EURC. Payments settle on-chain in seconds at near-zero network cost without credit card interchange fees (1.5–3.5%) or multi-day bank wire delays.
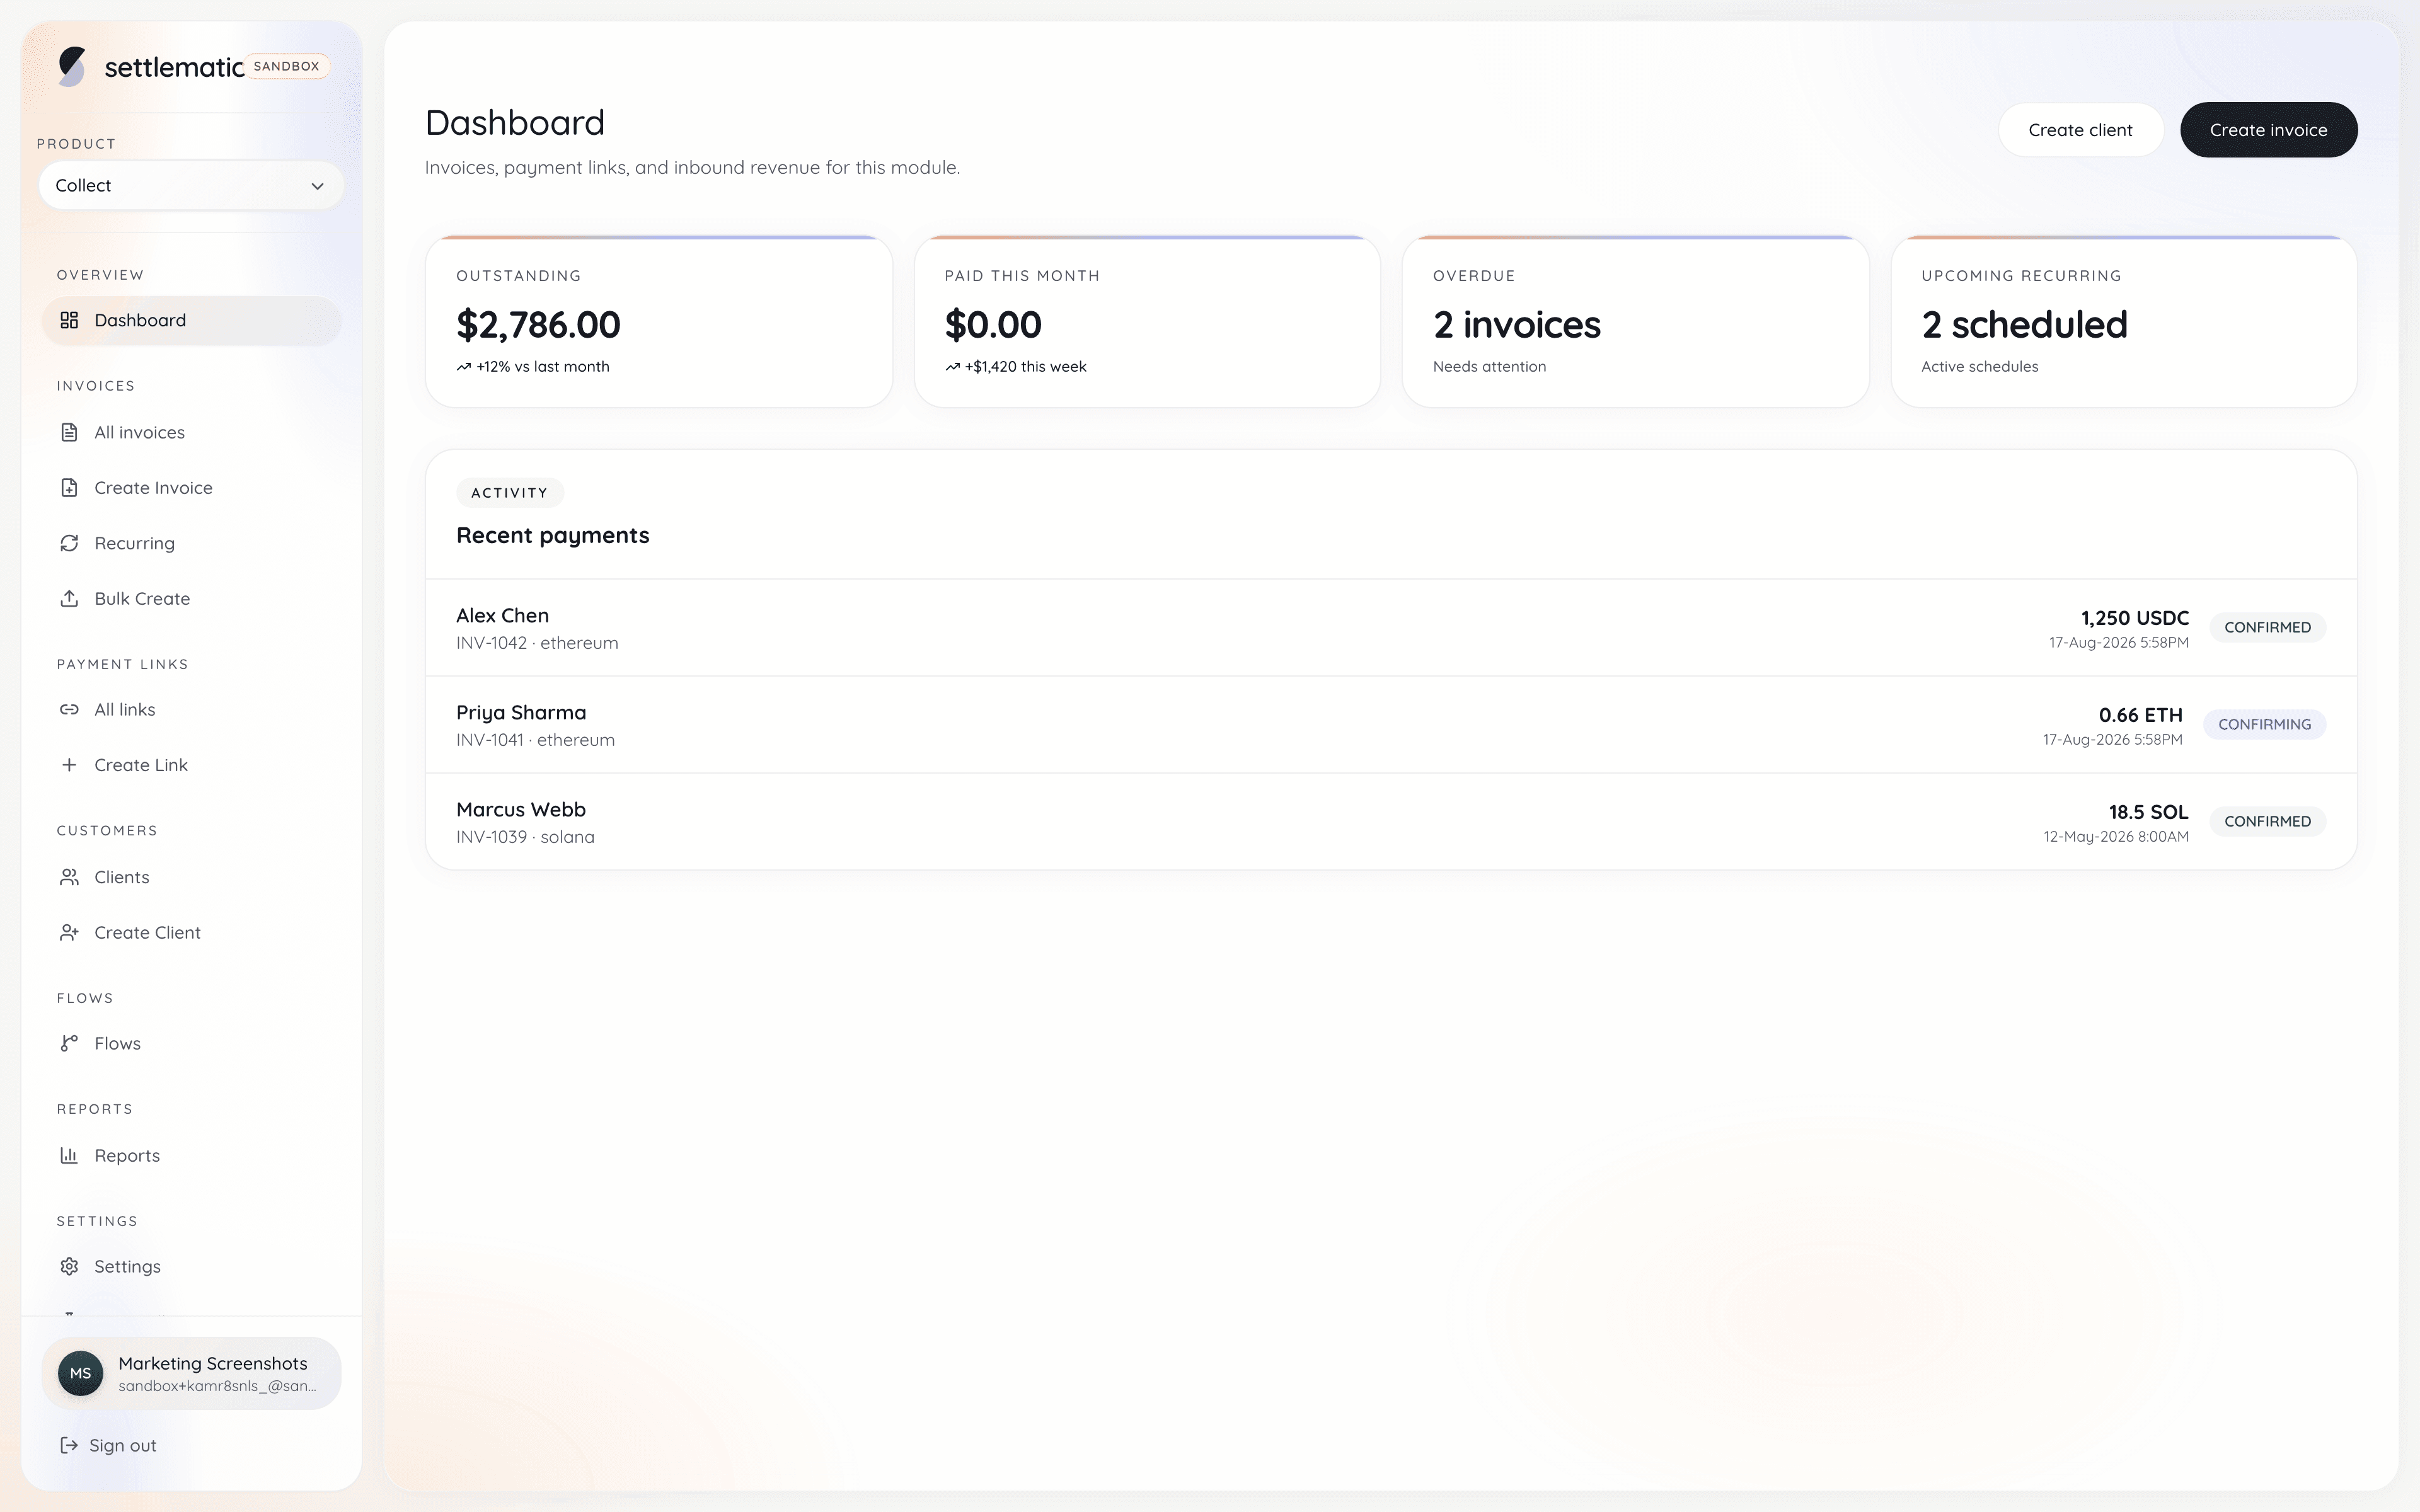
To accept stablecoin payments, businesses issue fiat-denominated invoices or checkout links that generate unique deposit addresses for assets like USDC, USDT, and EURC. Payments settle on-chain in seconds at near-zero network cost without credit card interchange fees (1.5–3.5%) or multi-day bank wire delays. Non-custodial platforms bind checkout addresses directly to merchant-controlled wallets at issuance, ensuring funds never pass through a intermediary ledger balance.
As global commerce increasingly shifts toward digital rails, stablecoins have evolved from crypto-native trading collateral into a mainstream enterprise payment mechanism. B2B firms, SaaS vendors, agencies, and cross-border exporters accept stablecoin payments to streamline treasury operations, eliminate credit card chargebacks, and settle international transactions instantly.
At Settlematic, we build non-custodial crypto invoicing and payment gateway software. In this guide, we walk through the mechanics of stablecoin payment acceptance, asset choices, infrastructure selection, regulatory considerations, and step-by-step implementation for modern finance teams.
What are stablecoin payments and how do they work?
A stablecoin is a cryptographic token issued on a blockchain whose value is pegged 1:1 to a fiat currency—most commonly the US Dollar (USD) or Euro (EUR). Unlike volatile cryptocurrencies such as Bitcoin or Ether, collateralized stablecoins like USDC (issued by Circle) and USDT (issued by Tether) maintain full reserve backing in short-term government treasuries, bank deposits, and cash equivalents.
When a merchant accepts a stablecoin payment, the checkout process mirrors traditional online billing, but the underlying rails differ fundamentally:
- Fiat Quoting: The invoice or checkout session is created in a national currency (e.g., $5,000 USD or €2,500 EUR).
- Rate Lock: The payment gateway queries live market liquidity to calculate the exact crypto amount required (e.g., 5,000.00 USDC) and locks the exchange rate for a set window (typically 15 to 30 minutes).
- Address Issuance: A unique, single-use deposit address is generated for the transaction across supported blockchains (Ethereum, Polygon, Solana, Tron, BSC, etc.).
- On-Chain Transfer: The buyer broadcasts a blockchain transaction from their web or mobile wallet to the deposit address.
- Instant Finality: Automated nodes observe the blockchain, confirm block finality, match the received amount with the invoice, and fire real-time webhooks to update ERP and accounting systems.
Why businesses are adopting stablecoins over traditional rails
Traditional financial infrastructure was built decades ago for domestic paper transactions and retrofitted for internet commerce. For international B2B payments, SWIFT wires pass through multiple correspondent banks, accruing cumulative fees ($25–$75+), foreign exchange markups (1–3%), and delays of 2 to 5 business days.
Credit cards provide faster consumer checkout but impose hefty interchange and processor fees (1.5% to 3.5%), processing volume caps, rolling reserves, and exposure to friendly-fraud chargebacks up to 120 days post-sale.
Stablecoins resolve these structural bottlenecks. Transfers settle 24 hours a day, 365 days a year, including weekends and bank holidays. Transaction fees on high-throughput networks like Polygon, Solana, and Arbitrum cost fractions of a cent, regardless of transaction size. A $100,000 B2B invoice costs the same few cents to transfer as a $10 payment.
Comparing stablecoins: USDC, USDT, and EURC
Not all stablecoins are created equal. Merchants accepting stablecoins must select assets based on customer demographics, reserve transparency, liquidity, and regulatory standing in target jurisdictions.
USDC (Circle): Highly transparent, USD-backed stablecoin with monthly reserve attestations conducted by independent accounting firm Deloitte. Circle is registered as a Licensed Money Transmitter in the US and holds a Markets in Crypto-Assets (MiCA) E-Money Institution license in the EU. USDC is favored by institutional enterprises, US/EU corporate buyers, and regulated fintechs.
USDT (Tether): The world's largest stablecoin by market capitalization and trading volume. Tether provides quarterly reserve reports attested by BDO Italy. USDT maintains dominant liquidity in emerging markets, Asia, Latin America, and cross-border trade corridors.
EURC (Circle): Circle's Euro-backed stablecoin, compliant with the EU MiCA framework. EURC allows European businesses to invoice and settle in Euros on-chain without exposing counter-parties to USD foreign exchange volatility. For detailed European compliance context, explore our guide to EURC payments for EU businesses.
For a deeper dive into reserve backing and operational differences, read our detailed comparison of USDC vs. USDT for business.
Stablecoins vs. traditional payment methods
| Feature | Credit Cards | SWIFT Wire | Custodial Gateway | Non-Custodial Settlematic |
|---|---|---|---|---|
| Processing Fee | 1.5% - 3.5% | $25 - $75 + FX fee | 0.5% - 2.0% | Flat $20-$49/mo (no % fee) |
| Settlement Time | 2 - 3 business days | 2 - 5 business days | 1 - 3 business days | Seconds to minutes |
| Weekend Settlement | No | No | No | Yes (24/7/365) |
| Chargeback Risk | High (up to 120 days) | Low | Low | Zero (cryptographically final) |
| Custody Risk | N/A (bank held) | N/A (bank held) | High (processor holds balance) | Zero (direct wallet settlement) |
| Cross-Border Friction | High (FX markups) | High (intermediary fees) | Moderate | None |
To analyze how stablecoins directly cut operational overhead against legacy banking, see our breakdown of stablecoins vs. bank wire transfers for B2B.
Custodial vs. Non-Custodial architecture: Protecting your revenue
When selecting a stablecoin payment processor, the architectural model determines who legally owns and controls your money while it moves from customer to merchant.
Custodial Processors (e.g., BitPay): The payment provider generates deposit addresses on its own internal ledger. When a customer pays, the processor receives the funds, holds the balance in its pooled accounts, and releases funds to your bank account or crypto wallet on a daily or weekly batch schedule. If the processor experiences insolvency, operational freezes, or banking delays, your revenue can be locked or subject to creditor claims.
Non-Custodial Settlematic Architecture: Settlematic generates unique deposit addresses that are cryptographically bound at issuance to your self-hosted wallet, multisig, or cold storage. Settlematic's servers never hold private keys or interim balances. Funds land directly in your wallet on-chain. Settlematic observes the blockchain, detects payment fulfillment, updates invoice status, and triggers webhooks—without ever possessing your money.
For checkout implementations on your custom web application, explore Settlematic Gateway.
Step-by-step guide to accepting stablecoin payments
Integrating stablecoin payment acceptance into your business workflow requires four straightforward steps:
Step 1: Set up a business wallet
Establish a secure corporate wallet or multisig (such as Safe) across your preferred blockchain networks (Ethereum, Polygon, Solana, etc.). Record the public receiving addresses.
Step 2: Connect settlement destinations in Settlematic
Log into your Settlematic account and configure settlement destination addresses. Settlematic uses HD derivation and counterfactual address binding to generate fresh, single-use receiving addresses for every invoice without ever requesting your private keys.
Step 3: Issue fiat-denominated invoices or checkout links
Create invoices in USD, EUR, or GBP using Settlematic Collect or embed the payment gateway via API. Set allowed payment assets (e.g., USDC on Polygon or USDT on Solana).
Step 4: Automated detection and accounting sync
When your customer remits payment, Settlematic detects block confirmation instantly, updates the invoice status to PAID, and exports reconciled CSV data for your accounting platform.
Honest trade-offs and operational considerations
A balanced payment strategy requires understanding the operational shifts involved in self-custodial stablecoin acceptance:
- Wallet Security Responsibility: Non-custodial settlement gives you full financial sovereignty, but your team is responsible for key management, seed phrase backup, and multisig governance.
- Off-Ramp Management: Settlematic settles stablecoins directly to your wallet. If your business needs fiat currency in a traditional bank account to pay local payroll, you must off-ramp via a corporate exchange account (such as Coinbase, Kraken, or Circle Mint).
- Irreversible Payments: On-chain transactions cannot be forcibly reversed. Refunds require issuing an outbound transfer from your wallet back to the customer.
Compliance, tax, and reporting standards
Accepting stablecoins is completely legal across major jurisdictions, provided businesses adhere to standard tax reporting and Anti-Money Laundering (AML) regulations:
- Tax Recognition: The IRS and international tax authorities treat stablecoin payments as gross revenue valued in local fiat at the exact moment of payment confirmation.
- Travel Rule Compliance: For high-value B2B transactions, platforms support Travel Rule data exchanges to verify originator and beneficiary identities between regulated entities.
- KYB/KYC Verification: Merchant onboarding protocols ensure compliance with global sanctions lists and financial intelligence standards.
Start accepting stablecoin payments today
Stablecoins represent the most efficient, cost-effective, and secure payment rails available to modern businesses. By eliminating intermediary take-rates and custodial risk, non-custodial invoicing allows merchants to keep 100% of their revenue while delivering a seamless checkout experience.
Test Settlematic in our free sandbox or explore our flat subscription pricing to start accepting stablecoins with zero percentage take-rates.
Sources
Frequently asked questions
- Why should a business accept stablecoin payments?
- Stablecoins offer instant, 24/7 cross-border settlement, eliminate credit card interchange fees (1.5–3.5%) and chargeback fraud, and provide guaranteed exact-amount payout without foreign exchange markups or correspondent bank delays.
- Which stablecoins should my business support?
- USDC (Circle) and USDT (Tether) cover over 90% of global dollar-denominated stablecoin demand. For European businesses operating under MiCA, Circle's EURC provides euro-denominated settlement backed 1:1 by euro reserves.
- Do I need a crypto wallet to accept stablecoin payments?
- Yes. In a non-custodial model like Settlematic, stablecoins settle directly to a digital wallet or cold storage address you control. If you prefer off-ramps, you can connect your business wallet to a licensed exchange to convert stablecoins into bank fiat.
- Are stablecoin payments subject to chargebacks?
- No. On-chain stablecoin transactions are cryptographically final once confirmed on the blockchain. There are no centralized card networks or acquiring banks that can force chargebacks, eliminating friendly fraud.
- How do stablecoin payments impact tax and accounting?
- Revenue is recognized in your local fiat currency (USD, EUR, GBP) based on the fair market value at the exact time of payment confirmation. Keeping automated transaction logs with timestamps and transaction hashes simplifies month-end reconciliation.